 Reynand Wu
The international investment landscape is currently undergoing a period of rapid transformation, characterized by shifting supply chains, geopolitical realignments, and a global race for high-level technical talent. In response to these pressures, a prominent industry committee has issued a comprehensive set of recommendations to the Taiwan government, advocating for a modernized tax environment and more robust trade mechanisms. While the committee expressed appreciation for the government’s ongoing efforts to enhance transparency and improve the domestic tax climate, it emphasized that further alignment between tax incentives and practical industry needs is essential to ensure Taiwan remains a top-tier destination for inbound investment and international professionals.
The core of the committee’s proposal focuses on four critical areas: the expansion of tax exemptions for foreign professionals, the simplification of offshore trust filing procedures, the correction of technical distortions in real estate taxation, and the implementation of zero-tariff treatment for vehicles originating from the United States. By addressing these regulatory hurdles, the committee argues that Taiwan can significantly reduce compliance burdens, achieve tax neutrality, and foster a more foreigner-friendly administrative interface.
Modernizing the Employment Gold Card Tax Framework
One of the most pressing concerns raised involves the Act for the Recruitment and Employment of Foreign Professionals. Since its inception, the act has been a cornerstone of Taiwan’s strategy to attract global experts through the Employment Gold Card scheme. Under Article 22 of the Act, high-level foreign professionals who reside in the Republic of China (R.O.C.) for at least 183 days in a taxable year and earn an annual salary exceeding NT$3 million are eligible for a significant tax incentive: one-half of the income exceeding that threshold is exempt from gross consolidated income tax.
However, the committee pointed out a significant gap in how "income" is defined under current administrative rulings. According to Ministry of Finance Letters No. 0930451436 and No. 09604503990, the gains from Employee Stock Options (ESOs)—specifically the amount by which the fair market value exceeds the exercise price—are classified as "Other Income" rather than "Salary Income." This classification also extends to equity acquired through global share schemes or the transfer of treasury shares under the Company Act.
In the modern corporate world, particularly within the technology and R&D sectors that Taiwan seeks to court, equity-based compensation is a standard and substantial component of a senior executive’s remuneration package. By strictly limiting tax incentives to "Salary Income," the current law effectively excludes a large portion of a professional’s total compensation from the promised tax relief. The committee argues that this misalignment diminishes the attractiveness of the Gold Card and contradicts the legislative intent of the Act. They recommend that the Ministry of Finance evaluate the feasibility of incorporating equity-based payments into the scope of applicable tax exemptions to reflect global compensation practices.
Enhancing Transparency for Offshore Trustees
The second major recommendation addresses the procedural difficulties faced by offshore entities following recent tax rulings. In July 2024, the Ministry of Finance issued a ruling regarding Controlled Foreign Corporations (CFCs). It stipulated that when trust assets include a CFC and meet specific taxation requirements, offshore trustees must complete trust income filings for the preceding year by January 31.
While the move is intended to increase tax transparency and align with international anti-avoidance standards, the implementation has proven challenging. Most offshore trustees do not possess Chinese language proficiency, yet the filing forms and guidance are primarily issued in Chinese and are subject to frequent updates. This creates a significant compliance barrier and increases the risk of filing errors.
To mitigate these issues, the committee urges the National Taxation Bureau to publish English-language trust filing templates and comprehensive guidance in a timely manner. Providing these resources would allow trustees sufficient time to comprehend the evolving requirements, thereby enhancing the efficiency and accuracy of the filing process. Such a move is seen as a necessary step in creating a more "foreigner-friendly" administrative environment that reduces the friction of doing business in Taiwan.
Rectifying Distortions in the House and Land Transactions Income Tax
A third area of focus involves the "Taiwan real-property-rich" (land-rich) company determination under the House and Land Transactions Income Tax (HLTIT 2.0) regime, which was introduced in July 2021. Currently, if an individual or enterprise holds more than 50% of a company, and 50% or more of that company’s value is attributable to Taiwan real estate, the disposal of those shares is subject to the new tax regime.
The committee identified a technical flaw in the calculation formula that often leads to distorted results. Currently, the "numerator" of the ratio is based on the fair market value (FMV) of the real property, while the "denominator" is based on the company’s recorded net asset value (NAV). Because NAV accounts for liabilities, a company with high debt or a high dividend payout policy will have a smaller denominator, which artificially inflates the ratio. This can lead to companies being classified as "land-rich" even when their primary business is not real estate.
To align with international standards, specifically the OECD Model Tax Convention, the committee suggests three specific reforms:
- Revise the Denominator: Use the company’s total asset value rather than net asset value, as total assets provide a more accurate picture of a company’s composition without the distortion of debt.
- Exempt Business M&As: Exclude share exchanges conducted under the Business Mergers and Acquisitions Act from this regime, provided there is no change in ultimate beneficial ownership. This would prevent the tax from hindering legitimate corporate restructurings.
- Grandfather Old-Regime Properties: Exclude real properties acquired before the 2016 tax reform from the land-rich determination if the investor also held the shares prior to that date.
Industry analysts suggest that these changes are vital for maintaining a healthy M&A market in Taiwan, as the current "distorted" ratio may discourage multinational enterprises from pursuing strategic investments or internal reorganizations.
Strengthening U.S.-Taiwan Trade through Automotive Tariff Reform
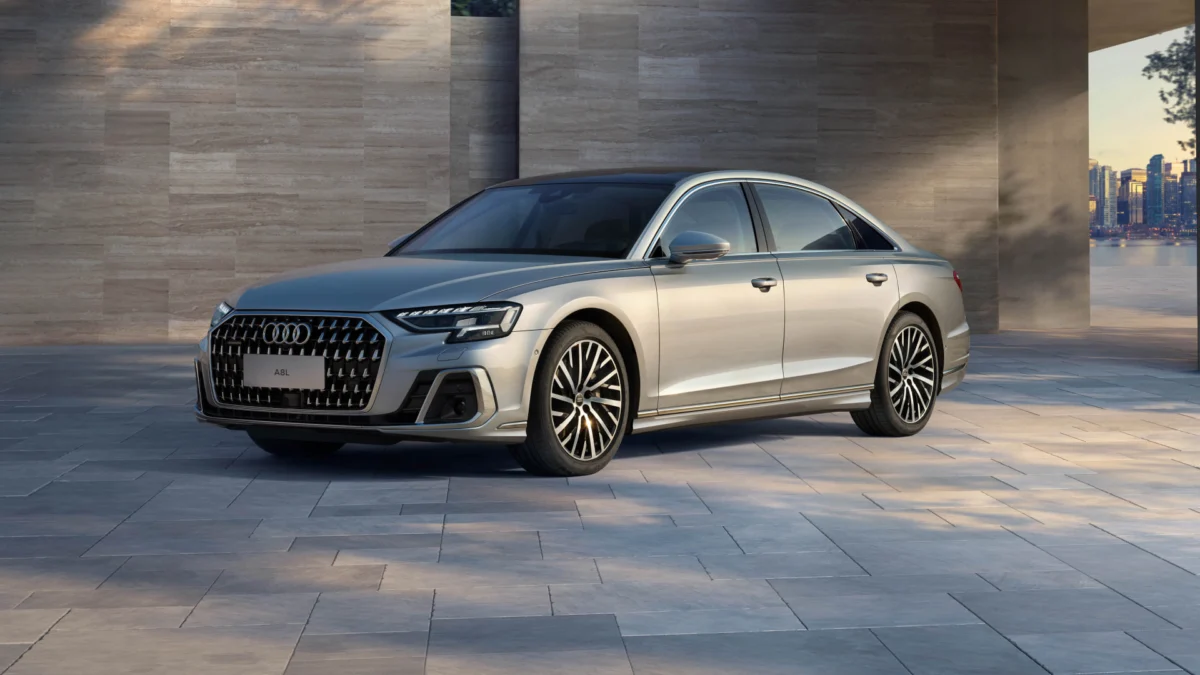
Finally, the committee turned its attention to bilateral trade relations, specifically with the United States. Amid ongoing uncertainty in global tariff regimes, the committee recommended that Taiwan implement zero-tariff treatment for U.S.-origin vehicles across L (motorcycles), M (passenger cars), and N (commercial vehicles) categories.
The United States is a primary source of innovation in the automotive sector, particularly regarding electric vehicles (EVs) and intelligent transport systems. By eliminating customs duties on these vehicles, Taiwan would not only support its own decarbonization and "Net Zero 2050" goals but also reinforce its strategic economic partnership with the U.S. This move is seen as a way to lower costs for consumers and logistics businesses while improving Taiwan’s standing as a regional hub for advanced automotive technology.
Furthermore, the committee proposed the introduction of retroactive tariff relief. Because vehicle procurement involves long shipping and "homologation" (certification) cycles, many importers commit to orders months in advance. A transitional refund mechanism would ensure that businesses that imported vehicles just prior to a policy change are not unfairly penalized, thereby maintaining market stability and investor confidence.
Chronology of Relevant Regulatory Milestones
To understand the context of these suggestions, it is helpful to look at the timeline of Taiwan’s recent tax and trade evolution:
- January 2016: Taiwan implements the first phase of the House and Land Transactions Income Tax, creating a "dual-track" system for properties acquired before and after this date.
- November 2017: The Act for the Recruitment and Employment of Foreign Professionals is passed, introducing the Employment Gold Card.
- July 2021: HLTIT 2.0 takes effect, extending the tax to "land-rich" company share transfers to curb real estate speculation.
- January 2023: Taiwan officially implements Controlled Foreign Corporation (CFC) rules to align with global minimum tax standards (OECD Pillar Two).
- July 2024: The Ministry of Finance issues specific rulings regarding the filing obligations of offshore trustees under the CFC regime.
- January 2025: The first major filing deadline for offshore trustees under the new CFC trust guidelines.
Broader Impact and Implications
The recommendations put forward by the committee reflect a broader desire for Taiwan to transition from a manufacturing-heavy economy to a global hub for high-value services, technology, and finance. The proposed changes to the Employment Gold Card tax treatment are particularly significant; as global competition for AI and semiconductor talent intensifies, the ability to offer tax-efficient equity packages could be a deciding factor for top-tier professionals choosing between Taiwan, Singapore, or the United States.
On the trade front, the suggestion for zero-tariff treatment on U.S. vehicles aligns with the spirit of the U.S.-Taiwan Initiative on 21st-Century Trade. While such a move would require careful negotiation and legislative approval, it represents a proactive step toward a more integrated bilateral economic relationship.
In conclusion, while Taiwan has made commendable strides in improving its investment climate, the committee’s report serves as a reminder that regulatory frameworks must be dynamic. By refining the technicalities of real estate taxation, embracing English-language administrative transparency, and modernizing compensation-related tax laws, Taiwan can better position itself as a resilient and attractive destination for global capital and talent in an increasingly volatile world. Government officials are expected to review these suggestions in the coming months as part of the annual policy planning cycle.

 Ammar Sabilarrohman
 Suro Senen