 Raul Delapena Setiawan
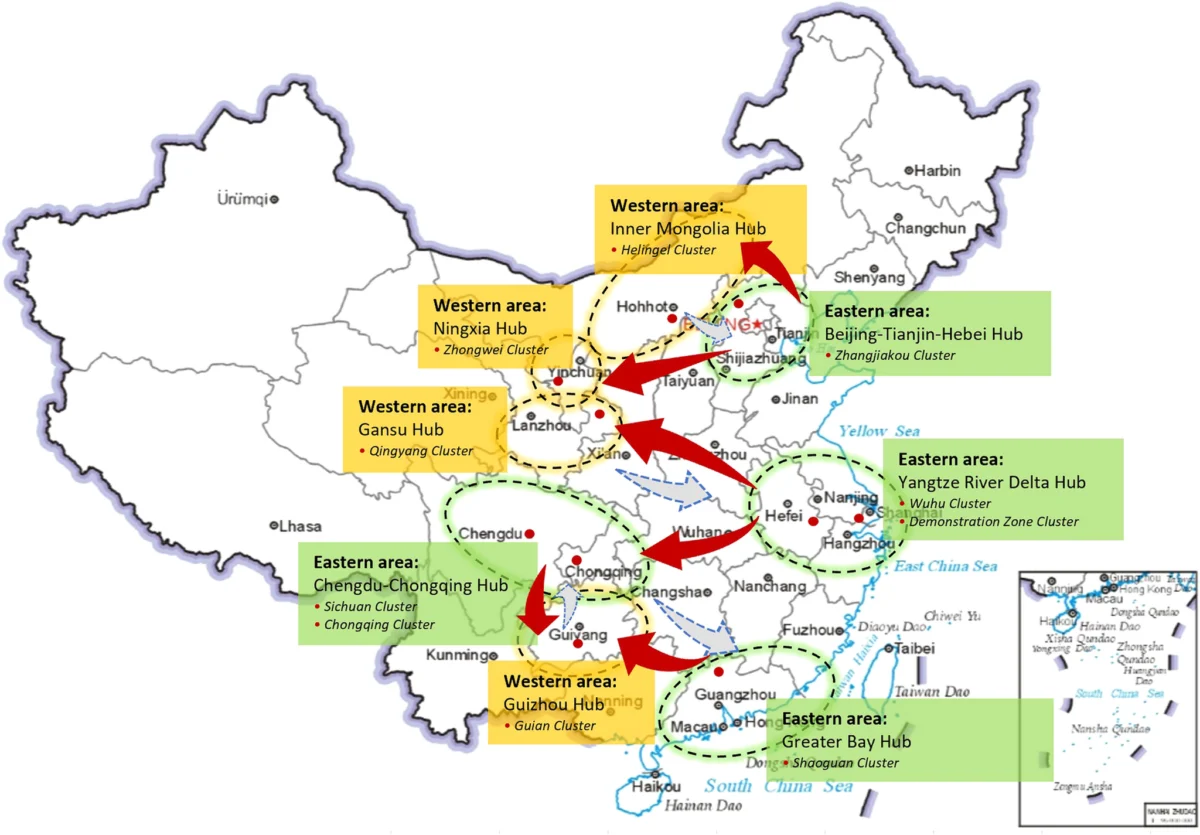
The meteoric rise of artificial intelligence (AI) is colliding with a fundamental physical constraint: the global electricity grid. As technology giants push the boundaries of AI model complexity and deploy increasingly vast computing infrastructure, the digital revolution is igniting an unprecedented surge in demand for physical energy. At the epicenter of this burgeoning challenge lies East Asia, the indispensable industrial powerhouse driving the global hardware supply chain.
Mainland China, home to the world’s second-largest data center market, also stands as the globe’s preeminent electronics manufacturing hub, responsible for approximately 36% of worldwide electronics output. Taiwan, a linchpin in the semiconductor landscape, dominates the production of the most advanced semiconductors and serves as the leading manufacturing base for AI servers. South Korea, meanwhile, spearheads the memory chip industry, with giants like Samsung Electronics and SK hynix holding commanding positions in DRAM and NAND flash memory. Together, these three East Asian economies occupy critical nodes across the interconnected sectors of data centers, semiconductors, server manufacturing, and memory chips, all of which form the bedrock of modern AI capabilities.
However, this computing boom carries a substantial environmental toll. In 2024 alone, data centers globally consumed an estimated 415 terawatt-hours (TWh) of electricity, representing about 1.5% of total global electricity consumption. The International Energy Agency (IEA) reports that this electricity usage had been escalating at an annual rate of roughly 12% over the preceding five years. Compounding this concern, Greenpeace East Asia projects that global electricity demand specifically for AI chip manufacturing could escalate by an astonishing 170-fold between 2023 and 2030. Given the concentration of logic and memory chip production for AI hardware in East Asia, a significant portion of this projected manufacturing burden would inevitably fall upon Taiwan, South Korea, and Japan.
Recognizing the urgency to address this growing challenge and chart a cleaner trajectory, Greenpeace East Asia convened a global webinar on August 6th. The event brought together leading experts in energy policy and climate technology from the United States, Taiwan, and South Korea. The primary objective was to pivot the discourse from the abstract necessity of decarbonizing AI to the concrete strategies required for building a clean and resilient AI supply chain.
"We aim to foster shared momentum for a clearer and more sustainable AI and technology industry," stated Dr. Junyan Liu, deputy program director at Greenpeace East Asia, in her opening remarks. "We strongly believe that by partnering directly with industry leaders, we can transform complex environmental hurdles into viable, high-impact business models for the long haul." The webinar served as a crucial platform for dialogue, bringing together diverse perspectives to confront the intertwined demands of technological advancement and environmental stewardship.
Scaling Clean Tech: Lessons from China’s Industrial Policy in a Shifting Global Landscape
Bridging the AI power gap necessitates a profound understanding of how clean technologies can be scaled effectively at an industrial level. China’s remarkable ascent in sectors such as solar energy, electric vehicles (EVs), battery technology, and grid infrastructure offers a compelling case study and valuable lessons for the rapid deployment of clean technologies amidst surging demand.
Dr. Kyle Chan, a Fellow at the Brookings Institution’s John L. Thornton China Center, elaborated on China’s strategic approach, highlighting how the nation achieved end-to-end dominance across raw materials to finished components. This was accomplished through a deliberate process of absorbing foreign technology, adapting it rapidly, and co-developing robust local supply chains. Proactive local governments played a pivotal role, accelerating this push by providing essential infrastructure, land, and crucial policy support, creating an ecosystem conducive to innovation and scale.
"China’s cleantech policy wasn’t a single linear path toward becoming a powerhouse," Dr. Chan explained. "It involved constant pivots, strategic shifts, and adaptation along the way. China made a broad bet across multiple technologies, and it paid off." This diversified approach, rather than placing all its bets on a single technological winner, allowed Chinese manufacturers to cater to different market needs while leveraging scale and supply-chain flexibility to drive down costs. Furthermore, the country’s established heavy industries provided crucial synergies with newer clean-energy sectors. For instance, its shipbuilding expertise has been instrumental in constructing offshore-wind installation vessels.
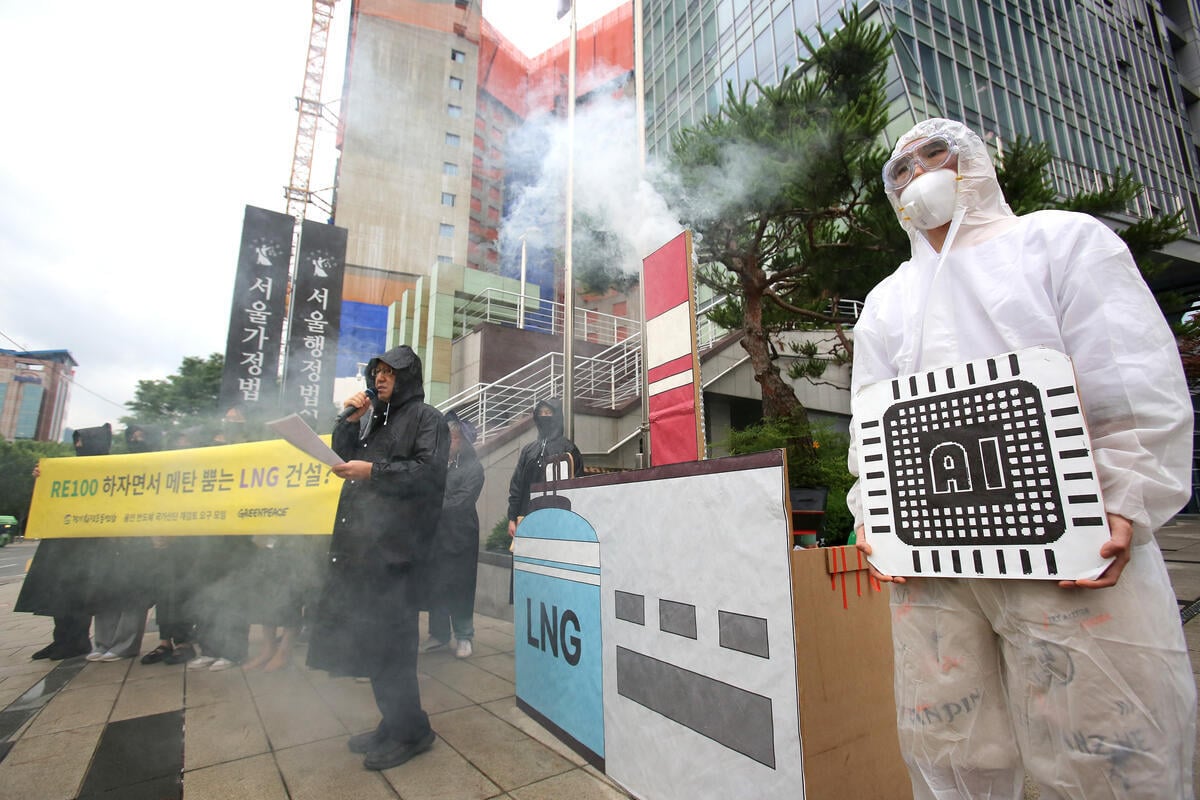
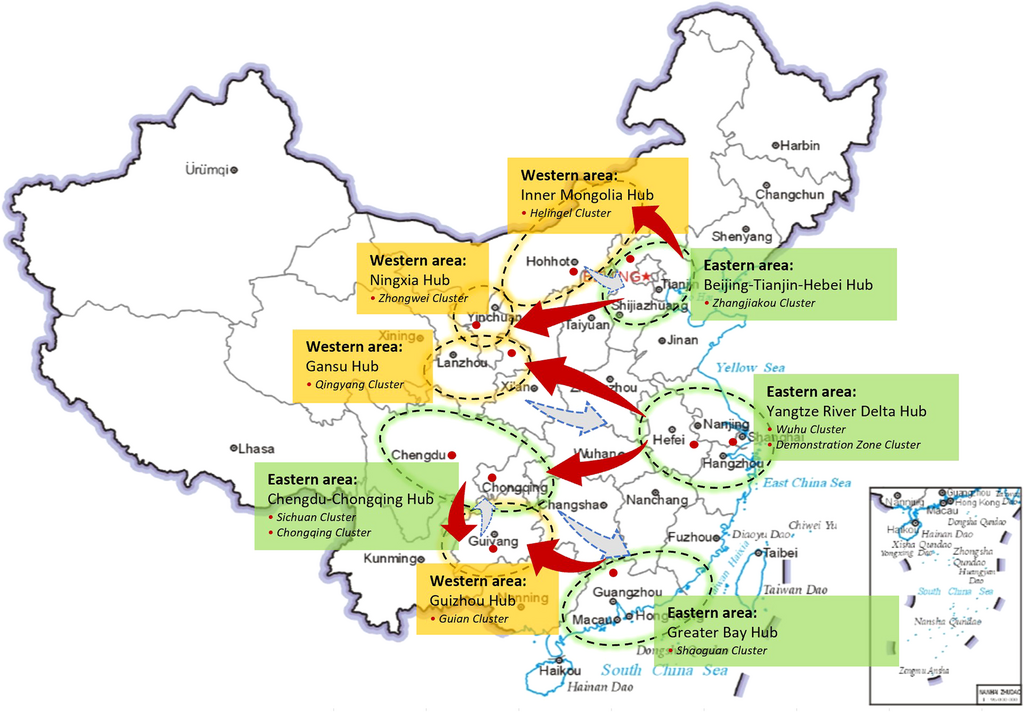
More recently, China has begun applying these integrated principles to the development of its data center infrastructure. Through the ambitious "East-West Computing Resources Transmission Project" (EWCRT Project), national policies are actively encouraging companies to relocate energy-intensive and less latency-sensitive computing workloads to the resource-rich western provinces. These regions offer abundant land and substantial wind and solar energy resources. The processed data and resulting services can then be efficiently delivered to users in coastal cities via the nation’s extensive computing networks. This strategic geographical redistribution aims to optimize energy consumption and leverage renewable resources more effectively for the burgeoning digital economy. As Chinese cleantech companies increasingly expand their global footprint, this integrated, adaptive approach offers significant insights for powering the AI era more sustainably worldwide.
The Economics of AI Power: Why Renewables Present the Winning Proposition in South Korea
In South Korea, the escalating demand from AI infrastructure is not merely a challenge but a significant catalyst for accelerating the nation’s transition to clean energy. Jongkyu Kim, founder and chief executive officer of 60Hz and chair of the Korea Climate Tech Association, articulated this perspective during the webinar.
South Korea has recently unveiled a suite of ambitious mega-projects with a combined investment approaching approximately 1,500 trillion won (roughly US$1 trillion). This substantial package includes the construction of four new semiconductor fabrication plants by industry leaders Samsung Electronics and SK hynix, alongside regional robotics initiatives. Crucially, it sets a target of establishing 18.4 gigawatts (GW) of AI data center capacity by 2035. This projected capacity would represent a significant portion, equivalent to roughly 18-19%, of South Korea’s recent peak electricity demand, underscoring the scale of the energy challenge and opportunity.
"AI has become an electricity story," Kim emphasized, quoting Sam Altman’s observation that "the cost of intelligence should eventually converge to near the cost of electricity." He continued, "If true, AI competition becomes a race for the cheapest electricity, and future-proof sources will win." This statement reframes the AI race not just as a technological arms race but as an economic contest heavily influenced by energy costs.
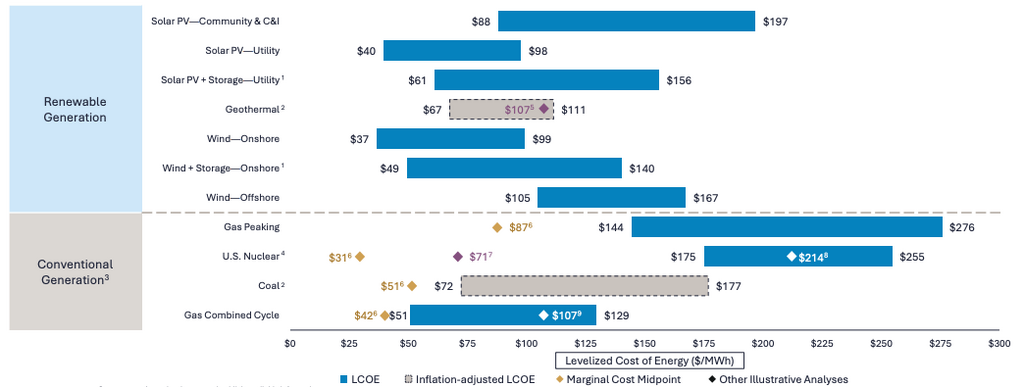
Kim presented a compelling economic argument for prioritizing renewables over fossil fuels or nuclear power. Citing Lazard’s 2026 Levelized Cost of Energy (LCOE+) Report, he highlighted that unsubsidized renewable energy sources consistently emerge as the most cost-competitive option for new-build generation on a dollar-per-megawatt-hour basis. This economic advantage is particularly pertinent in the context of AI, where sustained, high-volume energy consumption makes cost efficiency a paramount consideration.
"AI is not a burden on the energy transition; it is a catalyst," Kim asserted. "Korea has anchored its AI build-out to renewables by location, law, and policy. Industry leaders have signed on to RE100, and the underlying economics close the loop. If the cost of AI is the cost of power, zero-marginal-cost renewables will win." This vision posits that the growing energy demands of AI can serve as a powerful driver for accelerating renewable energy adoption, creating a virtuous cycle of technological advancement and environmental sustainability.
Overcoming Bottlenecks in Taiwan’s Critical Chip Industry Amidst Growing AI Demand
As a global leader in the production of advanced chips and AI servers, Taiwan stands as a critical engine powering the world’s computing capabilities. Allissa Tai, RE100 representative in Taiwan at the Chung-Hua Institution for Economic Research (CIER), detailed the structural obstacles and emerging opportunities that manufacturers face in securing a reliable supply of renewable electricity for their operations.
Taiwan’s Ministry of Economic Affairs forecasts an average annual electricity demand growth of 2.5% from 2026 to 2035, a significant portion of which is attributed to the expansion of semiconductor fabrication plants, AI data centers, and the increased cooling demands associated with these energy-intensive facilities. CIER estimates that AI and semiconductor-related projects alone could necessitate an additional 4.32 GW of electricity capacity by 2030, underscoring the immense pressure on the island’s energy infrastructure.
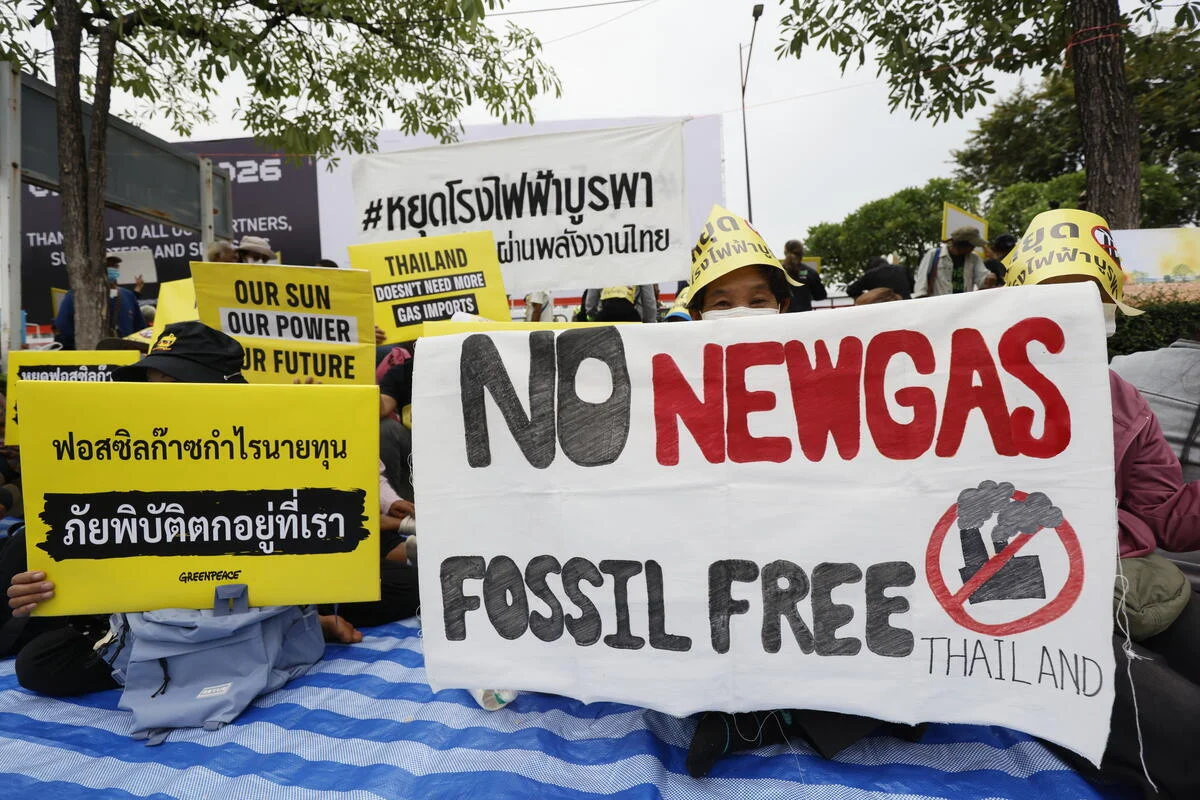
In response to this projected demand surge, Taiwan’s Ministry of Economic Affairs has outlined plans to add approximately 26 GW of new natural-gas-fired power generation capacity by 2035. However, this strategy raises concerns given Taiwan’s heavy reliance on imported energy, with over 94% of its energy needs met through imports in 2024. A greater dependence on imported fossil fuels would expose the island to the inherent volatilities of international energy markets, potential shipping disruptions, and broader geopolitical risks, thereby jeopardizing its energy security and economic stability.
While major global technology corporations, including Google and Apple, are actively pursuing 100% renewable electricity targets for their operations and supply chains, the collective corporate procurement of RE100 members accounts for only about 5% of Taiwan’s total renewable generation, according to recent analyses by CIER and The Climate Group. This disparity highlights significant structural barriers that impede the widespread adoption of clean energy within Taiwan’s crucial technology sector.
Key obstacles identified include the limited availability of renewable energy power purchase agreements (PPAs) that are affordable and accessible to a broad range of companies, particularly small and medium-sized enterprises within the supply chain. Furthermore, there are challenges related to the development of dedicated renewable energy infrastructure that can meet the specific and often large-scale demands of the semiconductor industry. Regulatory frameworks, while evolving, still present complexities that can slow down the procurement and integration of renewable energy sources. The lack of sufficient grid infrastructure to seamlessly integrate intermittent renewable sources also poses a significant challenge. Finally, the need for greater policy stability and long-term commitment from the government is crucial to provide the certainty required for substantial private sector investment in renewable energy.
"To power the AI boom cleanly, we need energy infrastructure built at scale," Tai stated. "That requires policy stability, social consensus, and cross-party alignment. Transitioning to renewables is not just about climate; it is the bedrock of Taiwan’s economic security and global competitiveness." Her remarks underscored the imperative for a cohesive, long-term strategy that aligns Taiwan’s technological prowess with its energy future.
An Action Plan for a Clean AI Ecosystem: Charting a Sustainable Future
To effectively align the rapid growth of artificial intelligence with global climate objectives, the webinar’s distinguished panelists collectively outlined three crucial, targeted reforms designed to foster a clean and sustainable AI ecosystem. These recommendations aim to provide a clear roadmap for policymakers, industry leaders, and stakeholders committed to navigating the complex energy demands of the digital age.
Firstly, the experts strongly advocated for the establishment of robust, long-term policy frameworks that prioritize and incentivize the development and deployment of renewable energy infrastructure. This includes setting ambitious, legally binding targets for renewable energy generation and consumption, particularly for energy-intensive industries like AI and semiconductor manufacturing. Such policies should offer clear, predictable incentives, such as tax credits, feed-in tariffs, and streamlined permitting processes, to encourage private sector investment. Crucially, these frameworks must ensure policy stability to provide the necessary confidence for long-term capital allocation. The goal is to create an environment where investing in clean energy is not only environmentally responsible but also economically advantageous.
Secondly, the panelists emphasized the urgent need to foster greater collaboration and knowledge sharing between governments, industry stakeholders, and research institutions. This collaborative approach is essential for accelerating innovation in clean energy technologies and developing scalable solutions tailored to the specific needs of the AI sector. Encouraging public-private partnerships can help bridge the gap between technological advancements and their practical implementation. Initiatives such as the RE100 campaign, which brings together influential companies committed to 100% renewable electricity, exemplify the power of collective action. Expanding such platforms and fostering open dialogue can facilitate the identification and adoption of best practices, while also addressing common challenges across different regions and sectors.
Thirdly, the experts called for a strategic geographic redistribution of energy-intensive computing infrastructure, coupled with significant investments in grid modernization and smart grid technologies. This involves identifying regions with abundant renewable energy resources, such as wind and solar power, and incentivizing the relocation of data centers and manufacturing facilities to these areas. Simultaneously, modernizing the electricity grid is paramount to ensure its capacity to handle the intermittency of renewable sources and to efficiently transmit clean energy across vast distances. Investing in smart grid technologies, including advanced metering, demand-side management, and energy storage solutions, will be critical for optimizing energy distribution, enhancing grid resilience, and ensuring a stable power supply for the ever-growing demands of the AI revolution. By integrating these strategies, the aim is to create a more efficient, resilient, and environmentally sound energy foundation for the future of AI.

 Suro Senen
 Ammar Sabilarrohman